
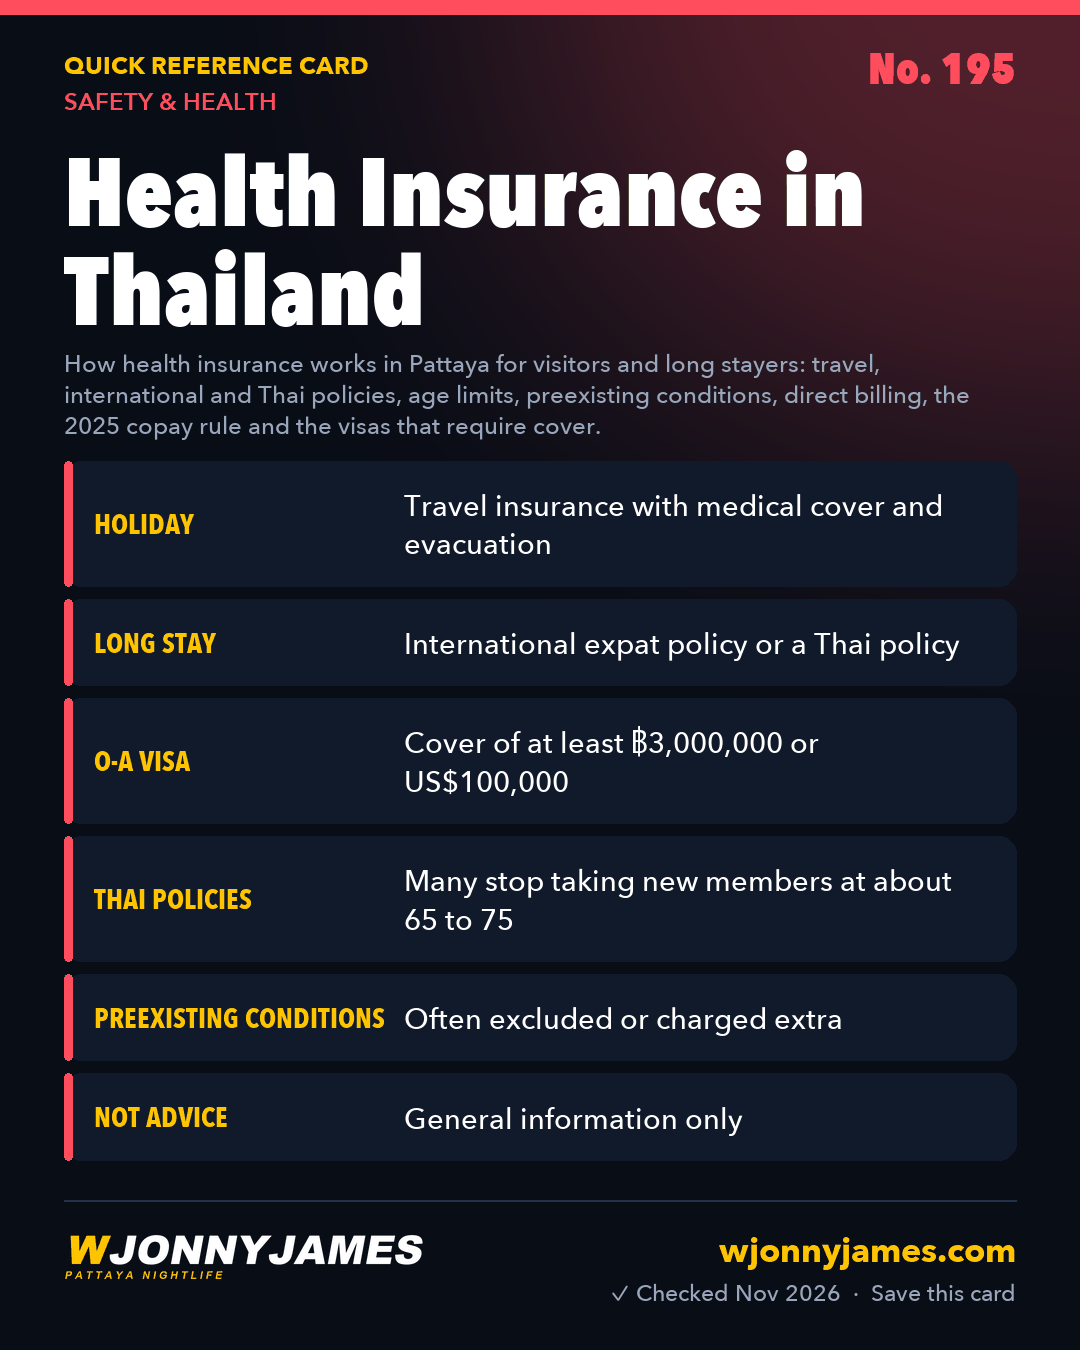
Quick answer: Pattaya’s private hospitals are good, but expensive, and can ask for a deposit or an insurer’s guarantee before big treatment. On holiday, the usual answer is travel insurance with high medical and evacuation limits. If you live here, the choice is between an international expat policy (wider cover, higher price, more flexible on age) and a Thai policy from a Thai insurer (cheaper, mainly Thailand, with stricter entry ages). Buy while you are healthy: conditions you already have are often excluded. One visa makes cover compulsory: the Non-Immigrant O-A retirement visa, applied for abroad, needs at least ฿3,000,000 or US$100,000 of cover. This page is general information, not financial advice, and we don’t recommend any insurer.
At a glance
| Type | Who it suits | Main things to check |
|---|---|---|
| Travel insurance | Holidays and trips of a few weeks or months | Medical and evacuation limits, motorbike and alcohol exclusions, trip length |
| International expat policy | People living here, often older or with homes in two countries | Area of cover, deductible, direct billing, how preexisting conditions are treated |
| Thai policy (Thai insurer) | People living here long term who mostly need treatment in Thailand | Entry and renewal ages, copay clause, contract language |
| No insurance, own fund | Only those who could pay a large bill themselves | Public hospital option, cost estimates before treatment |
Visiting: travel insurance
Travel insurance is built for trips, not for living here: it pays for emergencies, not checkups or ongoing care. Look for:
- Emergency treatment and hospital stays with a high limit, and medical evacuation or repatriation.
- Motorbike cover, and what it demands. Most policies want a licence valid for the bike and a helmet. See renting a scooter and international driving permit.
- Alcohol exclusions: claims after drinking are often refused.
- Activities you plan, like diving or adventure sports, and the longest trip the policy allows.
More detail is on travel insurance.
Living here: international or Thai policy
| International expat policy | Thai policy | |
|---|---|---|
| Price | Usually higher | Usually lower |
| Cover | Worldwide or regional, often including your home country | Mainly Thailand |
| Age to join | Often more flexible | Many plans stop new members at about 65 to 75 |
| Preexisting conditions | Sometimes covered for an extra premium or after a waiting period | Usually excluded |
| Language | English throughout | Check the contract language before you sign |
| 2025 copay rule | Generally outside the Thai rule | Can apply (see below) |
Sources differ on Thai age limits: one large Thai insurer’s plan accepts new applicants up to 65, while a December 2025 Thaiger guide says many local plans stop at 70 to 75. Check the renewal age as well as the joining age.
The Thai copay rule
Since 20 March 2025, Thai health policies can carry a copayment clause allowed by the insurance regulator (OIC). If you make three or more claims in a policy year for minor illnesses, such as flu, diarrhoea or headaches, and they add up to more than twice your premium, you pay 30% of your bills the next year. Sources report a second trigger for general illness claims at four times the premium, and 50% if you hit both. Major surgery and critical illness claims are reported not to count towards the triggers. Reports say the clause can come off once claims fall back below the limits. In practice, many people pay small visits themselves and keep the policy for real treatment.
Direct billing and deposits
- Direct billing means the insurer pays the hospital, so you don’t pay up front. Ask the insurer which Pattaya hospitals it bills directly, and carry your policy card.
- Without it, private hospitals may want a deposit or full payment, and you claim back later. Keep every receipt and medical report.
- For planned treatment, get a written estimate and ask the insurer to preapprove it.
- See hospital costs and hospitals and clinics.
Which visas require insurance
- Non-Immigrant O-A (retirement, applied for abroad): Thai embassy pages state cover for the whole stay of at least ฿3,000,000 or US$100,000, with a certificate signed by the insurer on the official form. Thai insurers must be on the approved long stay list. Some sources say the rule also applies when O-A holders extend inside Thailand; ask immigration. See retirement visa.
- Non-O retirement extensions inside Thailand: insurance usually isn’t required, which is why many people in Pattaya use that route. That doesn’t make going without cover wise.
- LTR visa: the Board of Investment asks for health cover of at least US$50,000, or one of its listed alternatives.
- DTV and tourist stays: no insurance requirement. See DTV visa and visa options.
Without insurance
- Public hospitals cost much less, with longer waits and less English. Clinics and pharmacies handle small problems cheaply. See pharmacies and medicines.
- Keep an emergency fund you can reach quickly. See emergency numbers.
Pro tip: healthcare here has been, every time, “a million times faster and smoother than the West.” I don’t have health insurance at the moment. That’s my own choice, based on a healthy, active lifestyle: no smoking, no alcohol, eating well. It isn’t advice. Your age, health and savings are different, so decide for yourself.
Before you buy
- Is outpatient care covered, or only hospital stays? What is the deductible?
- Does the insurer bill Pattaya’s hospitals directly?
- How are preexisting conditions treated, and what must you declare? Leaving things out can void a policy.
- What is the oldest age it renews to, and how fast do premiums rise with age?
- Is motorbike riding covered, and on what conditions?
- Dental: most travel insurance only covers emergency pain. See dentists in Pattaya.
Common questions
Do I need health insurance to visit Thailand? Not for a normal tourist stay, but travel insurance with medical cover is strongly advised because private hospital bills can be large.
How much cover does the O-A visa need? Thai embassy pages state at least ฿3,000,000 or US$100,000 for the whole stay, shown with the insurer’s signed certificate.
Can I get health insurance in Thailand over 70? Some Thai plans stop taking new members at 65, others later, and international insurers are often more flexible. Prices rise with age, so it is easier to start younger and keep renewing.
Sources
Checked 13 November 2026: Royal Thai Consulate General Los Angeles, Non-Immigrant O-A (updated 1 September 2026); Royal Thai Embassy Madrid, O-A health insurance requirements; Board of Investment, LTR brochure; Siam Legal, the copay rule from 20 March 2025; The Thaiger, healthcare at different ages (December 2025); Allianz Ayudhya, a Thai plan’s entry age (cited for the age rule only, not a recommendation). Sources differ on Thai entry ages and the copay triggers. Rules change; read the policy wording and ask the embassy or immigration. General information, not financial or legal advice.
Related pages
Ride along with Jonny
Every guide page comes from the nightly rides through Pattaya. Watch them, ask questions in the community, or help keep the camera rolling.
Watch the rides Join the Telegram Leave a tip Support the rides
 ไทย
 中文
 Русский
 한국어
 Deutsch
 Français